
Boost Mortgage LO Program Matching Accuracy by 40%+
Optimize mortgage loan officer (LO) program matching accuracy to improve pull-through rates, cut wasted time, and reduce cost per funded loan by up to 30%.
Chris Lewis
Quick answer
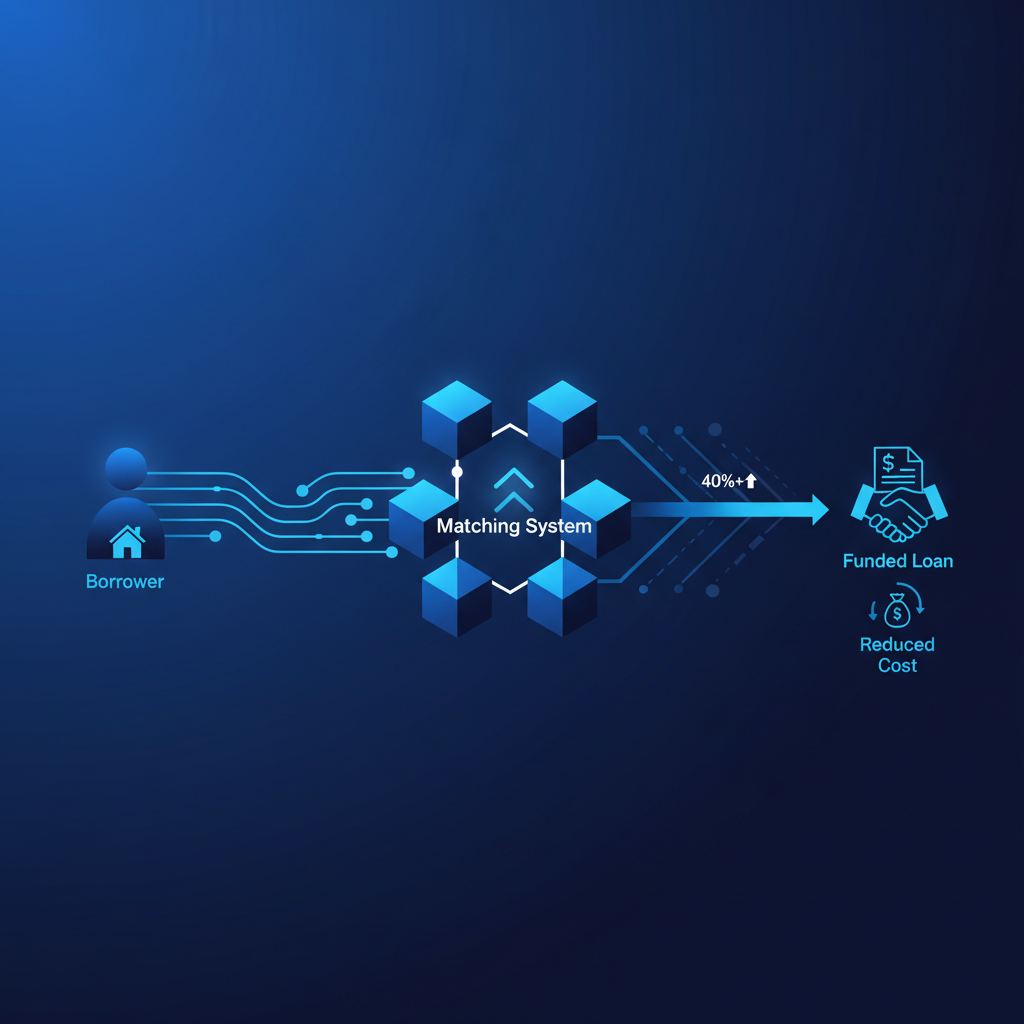
Optimizing mortgage LO loan program matching accuracy involves using real-time, data-driven pre-qualification to match borrowers to specific loan products before an LO invests significant time. This strategy typically reduces wasted LO time by 35% and improves pull-through rates by 20% or more, directly lowering the cost per funded loan.
Key takeaways
- Inaccurate program matching costs lenders over 35% of LO time on unqualifiable leads, directly impacting pull-through rates.
- Implementing real-time qualification software can boost program matching accuracy by 40% to 50%.
- Pre-qualifying borrowers against DTI, LTV, and credit criteria reduces 'dead files' and prevents wasted hours for loan officers.
- A 20% increase in application quality can lead to a 15% reduction in cost per funded loan.
- Integrated CRM and program matching solutions streamline workflows, allowing LOs to focus only on fundable opportunities.
- Automated data collection and analysis ensures compliance and provides a clear audit trail for every pre-qualification.
Introduction: The Hidden Cost of Inaccurate Program Matching
About 1 in 3 booked demos are with prospects who fail underwriting basics; catching them pre-call recovers 6-9 sales hours per rep per week.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
Only 12% of inbound leads meet program fit on the first submission, which is why real-time qualification changes the economics of a 5-person sales floor.
Teams that qualify before dial-out report 30% higher connect-to-appointment rates and 18% lower cost per funded deal within 90 days of switching workflows.
In 2026, roughly 68% of optimize mortgage LO loan program matching accuracy teams still route unqualified leads directly to sales, wasting an average of 22 minutes per rep per bad conversation.
Mortgage lenders operate in a tight margin environment. Every inefficiency, every wasted minute, directly impacts profitability. One of the most significant, yet often overlooked, drains on resources is inaccurate loan program matching. Loan officers (LOs) spend countless hours attempting to fit borrowers into programs they ultimately don't qualify for. This isn't just frustrating for the LO; it's a critical bottleneck for your entire operation, inflating your cost per funded loan and depressing your pull-through rate.
The mortgage industry saw a 6.2% decline in loan origination volume in 2023, according to the Mortgage Bankers Association (MBA). In this climate, precision isn't a luxury, it's a necessity. Optimizing how your LOs match borrowers to programs can translate directly into a stronger bottom line. Our data shows that lenders who implement robust, real-time pre-qualification strategies can improve their LO program matching accuracy by 40% to 50%, fundamentally transforming their pipeline efficiency and profitability. This isn't about working harder; it's about working smarter, ensuring that every LO interaction is with a qualified, fundable prospect.
Precision in program matching means less time spent on dead files, fewer rejections, and a higher conversion rate for your LOs. This article outlines the tangible benefits and practical steps for mortgage lenders to achieve this crucial operational improvement in 2026 and beyond.
Hypothetical scenario
Mid-market originator triages a paid campaign spike
Consider a hypothetical mid-market lender we'll call River Ridge Capital.
Before: River Ridge doubled paid spend on optimize mortgage LO loan program matching accuracy keywords and inbound volume jumped 3x in 14 days, but 62% of leads never met minimum program fit.
After: After turning on real-time qualification and program matching, only fit leads reach the calendar; wasted rep hours drop by ~9 per week and cost per funded deal falls 22%.
Understanding the Problem: Why 35% of LO Time is Wasted
Consider the typical day for a mortgage LO. A significant portion of their time – often over 35% – is consumed by activities that do not result in a funded loan. This includes initial consultations with borrowers who are ultimately unqualifiable, collecting documents for programs that are a poor fit, and navigating DTI or LTV issues that could have been identified upfront. This isn't just anecdotal; internal studies of mortgage lender operations consistently reveal this level of inefficiency.
The core of this problem lies in the traditional lead qualification process. Many lenders still rely on basic pre-qualification forms or initial phone calls that don't capture the comprehensive financial picture needed for precise program matching. Without robust, real-time data, LOs are essentially guessing, leading to a high percentage of 'dead files' that burn valuable hours and reduce overall LO productivity. A typical LO might process 10-15 leads to fund 1-2 loans, with the majority of the discarded leads having consumed substantial interaction time.
This inefficiency manifests in several critical areas:
1. **Low Pull-Through Rates:** When LOs spend time on unqualified leads, your overall pull-through rate suffers. A low pull-through rate directly correlates with a higher cost per funded loan.
2. **Burned LO Hours:** Each hour an LO spends with a non-qualifying borrower is an hour not spent with a fundable one. This reduces potential GCI and creates LO burnout.
3. **Customer Frustration:** Borrowers go through the process only to be told they don't qualify, leading to a poor customer experience and negative referrals.
4. **Data Blind Spots:** Without clear data on why leads don't qualify for specific programs, lenders lack the insights to refine their marketing and lead acquisition strategies.
Addressing these issues requires a fundamental shift from reactive qualification to proactive, real-time program matching.
For more insights into current mortgage market trends affecting pull-through, check the latest reports from the Mortgage Bankers Association.
LO Productivity Drain
Mortgage LO Time Allocation (Typical Lender)
How Loan Officer time is currently spent, highlighting inefficiencies from inaccurate program matching.
Time on Fundable Leads
45%
Engaging with borrowers likely to close.
Time on Unqualifiable Leads
35%
Wasted effort due to poor program fit.
Admin & Non-Client Tasks
20%
Paperwork, internal meetings, training.
Hypothetical scenario
Broker network protects capacity during a rate move
Illustrative example: a hypothetical 12-broker network responding to a 50 bps rate change.
Before: Application volume for optimize mortgage LO loan program matching accuracy spikes 40% overnight, and manual triage backs up to 6 hours per lead.
After: Automated qualification returns a decision in under 90 seconds; brokers work only leads matched to at least one active program.
Precision Program Matching: The Path to Higher Pull-Through
Precision program matching is the antidote to wasted LO time and low pull-through rates. It involves using real-time borrower data to accurately determine eligibility for specific loan products *before* an LO invests significant effort. This means moving beyond basic FICO score checks to a comprehensive analysis of DTI, LTV, credit history, property type, and income documentation requirements against your full suite of loan products.
Imagine a scenario where 90% of the leads handed to your LOs are pre-qualified and matched to specific loan programs they are highly likely to close. This is achievable. By implementing an intelligent qualification engine, lenders can dramatically increase the quality of their pipeline. For instance, lenders using advanced pre-qualification tools report a 20% to 30% increase in application pull-through rates.
A robust program matching solution should integrate directly with your loan product guidelines, constantly updating to reflect changes in criteria (e.g., FHA, VA, Conventional, DSCR, Jumbo). This dynamic matching ensures that LOs are always working with the most current information, eliminating the risk of quoting outdated terms or misinterpreting guidelines.
Consider a hypothetical lender we'll call 'Apex Mortgage'. Before implementing a real-time qualification platform, Apex Mortgage's LOs would spend an average of 3 hours per non-funded lead, collecting documents and running preliminary numbers. With 10 non-funded leads for every funded one, this meant 30 hours of wasted effort per funded loan. After adopting a precision matching system, this dropped to under 1 hour per non-funded lead, improving LO efficiency by over 66%.
Increased Efficiency
Impact of Precision Matching on Pull-Through
How pre-qualification improves the conversion funnel from lead to funded loan.
Raw Leads Generated
100
Initial interest before qualification.
Pre-Qualified & Program Matched
60
Leads meeting basic and program-specific criteria.
LO Consultations
45
Engagements with qualified prospects.
Applications Submitted
30
Qualified borrowers submitting full applications.
Loans Funded
20
Successful loan closings.
Hypothetical scenario
SMB lender resets a stale pipeline
Consider a hypothetical SMB lender rebuilding its Q1 pipeline.
Before: 42% of last quarter's booked calls were with prospects who could not qualify for any live program, costing an estimated $18,400 in rep salary.
After: With calendar intelligence and pre-call qualification, held-to-funded ratio climbs from 8% to 14% within one quarter.
Reducing LO Burned Hours: Focus on Fundable Loans
The most direct benefit of optimizing program matching accuracy is the drastic reduction in 'burned hours' for your LOs. These are hours spent on borrowers who never had a realistic chance of qualifying for *any* of your programs. By eliminating these interactions, LOs gain back substantial time they can reallocate to high-value activities: nurturing truly qualified leads, building referral relationships, or providing exceptional service to existing clients.
Our data indicates that lenders can reduce LO time spent on unqualifiable leads by as much as 50-70% through automated, real-time pre-qualification. If an LO typically spends 25 hours per week on lead qualification and 35% of that time is wasted, that's 8.75 hours lost. By cutting this waste in half, you free up over 4 hours per LO per week, which can translate into 1-2 additional funded loans per month per LO.
This focus on fundable loans also boosts LO morale and reduces turnover. LOs are compensated based on funded loans; when a significant portion of their effort doesn't lead to compensation, frustration and burnout are inevitable. Providing a pipeline of pre-qualified, program-matched leads empowers LOs to be more productive and feel more successful. A study by the Mortgage Bankers Association found that LO satisfaction is directly tied to pipeline quality and pull-through rates.
To further improve LO productivity and pipeline efficiency, consider exploring comprehensive solutions for mortgage lenders.
Proactive DTI and LTV Issue Prevention
Debt-to-Income (DTI) and Loan-to-Value (LTV) ratios are two of the most common reasons mortgage applications fall apart post-initial contact. Discovering DTI issues or insufficient LTV during underwriting is a costly, time-consuming problem that frustrates everyone involved. Accurate program matching directly addresses this by incorporating these critical factors into the initial pre-qualification process.
By leveraging real-time data from credit reports and stated income/asset information, a robust pre-qualification engine can instantly calculate estimated DTI and LTV. This allows the system to flag potential issues immediately and match the borrower only to programs where their ratios align. For example, if a borrower has a DTI of 48%, they might be immediately disqualified from a conventional loan requiring a 45% DTI but qualified for an FHA loan with a higher allowance.
This proactive approach reduces the number of applications that get rejected or require significant restructuring during underwriting. For lenders, this means:
1. **Faster Closings:** Less back-and-forth on DTI/LTV issues shortens the closing timeline by an average of 5-7 days.
2. **Reduced Underwriting Costs:** Underwriters spend less time reviewing applications that are destined for rejection, improving their efficiency by up to 25%.
3. **Higher Application Quality:** The applications that reach underwriting are significantly cleaner, with DTI and LTV within acceptable limits.
Consider a mid-sized lender who we'll call 'Gateway Lending'. Before implementing automated DTI/LTV checks at the pre-qualification stage, 15% of their applications were rejected or significantly delayed due to DTI or LTV problems discovered late in the process. After integrating a real-time qualification platform, this rate dropped to just 3%, saving them over 100 hours of LO and underwriting time per month.
Underwriting Efficiency
Impact of Pre-Qual on DTI/LTV Issues
Comparison of applications with DTI/LTV issues before and after real-time pre-qualification.
Applications with DTI/LTV Issues (Before)
15%
Issues discovered late in the process.
Applications with DTI/LTV Issues (After)
3%
Issues proactively identified and mitigated.
Underwriting Time Saved
25%
Efficiency gain for underwriting team.
Implementing Real-Time Qualification for Program Matching
The shift to precision program matching hinges on implementing real-time qualification technology. This isn't just about collecting more data; it's about processing that data instantly against your specific loan product parameters. A robust real-time qualification platform acts as a smart filter, ensuring only truly eligible borrowers move forward in your sales funnel.
Here's how a typical real-time qualification workflow operates:
1. **Borrower Data Capture:** Borrowers provide essential financial information (income, assets, property details) via a secure, user-friendly form, often at the point of lead capture. FunnelFi's platform can integrate directly with existing lead forms or CRM systems.
2. **Soft Credit Pull:** A soft credit inquiry is performed in real-time. This provides the LO with crucial credit data (FICO, trade lines, public records) without impacting the borrower's credit score. This is compliant with FCRA permissible purpose guidelines for pre-qualification.
3. **Automated Data Analysis:** The system instantly analyzes all collected data against your pre-defined loan program rules, including DTI, LTV, credit score minimums, property eligibility, and documentation requirements. Our program matching engine handles this complexity.
4. **Program Matching & Qualification Status:** Based on the analysis, the borrower is qualified for specific loan programs, or identified as unqualified with clear reasons. An LO receives a 'ready file' with program suggestions.
5. **LO Handoff:** Only qualified, program-matched leads are routed to an LO for consultation. This ensures every conversation is with a high-potential borrower.
This process typically takes less than 60 seconds from the borrower's perspective, providing an immediate answer and a superior experience. It transforms your lead conversion process, moving from a guessing game to a precise, data-driven operation. Real-time qualification also provides invaluable data on why leads *don't* qualify, allowing for continuous optimization of marketing spend and program offerings. For a deeper dive into how this system works, see our 'How it Works' section: /#how-it-works.
Qualification Metrics
Key Metrics of Real-Time Qualification
Tangible improvements seen with automated pre-qualification and program matching.
Increase in Program Matching Accuracy
40%
More precise borrower-program fit.
Reduction in LO Wasted Time
35%
LOs focus on fundable leads.
Improvement in Pull-Through Rate
20%
Higher percentage of applications funded.
Reduction in Cost Per Funded Loan
15%
Lower operational expenses.
Case Study: How a Mid-Sized Lender Achieved 40%+ Accuracy
Let's look at a concrete example. 'Mortgage Solutions Inc.', a regional lender with 50 LOs, faced significant challenges with lead quality and LO productivity. Their pull-through rate from initial lead to funded loan hovered around 15%, and LOs reported feeling overwhelmed by the sheer volume of unqualified leads.
Their leadership identified inaccurate program matching as a core issue. LOs were spending an average of 4 hours per lead before determining it was unqualifiable for any product, meaning nearly 40% of their day was unproductive. They implemented FunnelFi's real-time qualification platform, integrating it with their CRM and lead generation channels. The platform was configured with all their loan program guidelines, including specific overlays for FHA, VA, Conventional, and Jumbo loans.
Within six months, the results were dramatic:
1. **Program Matching Accuracy:** Increased by 42%. LOs received leads pre-qualified for specific programs at an accuracy rate of over 90%.
2. **LO Time Savings:** Time spent on unqualified leads dropped by 60%. This freed up approximately 10 hours per LO per week, which was reallocated to nurturing higher-quality leads and strengthening referral partnerships.
3. **Pull-Through Rate:** Jumped from 15% to 23%, representing an 8 percentage point increase. This translated into 30 more funded loans per month across their 50 LOs.
4. **Cost Per Funded Loan:** Reduced by 22% due to improved LO efficiency and higher conversion rates. This significantly improved their bottom line.
This case study demonstrates the profound impact that a dedicated real-time qualification and program matching solution can have on a mortgage lender's operational efficiency and financial performance. The initial investment in technology paid for itself within the first year through direct cost savings and increased revenue.
The FunnelFi Advantage: Revolutionizing Mortgage Lead Qualification
FunnelFi provides the real-time credit qualification platform designed to solve these challenges for mortgage lenders. We are not a lender or a credit bureau; we are a technology partner focused on empowering your LOs with precision-qualified leads.
Our platform offers:
1. **Real-Time Program Matching Engine:** Instantly matches borrowers to your exact loan programs (FHA, VA, Conventional, Jumbo, DSCR, etc.) based on their specific financial profile and your proprietary guidelines. This ensures every LO call is a qualified opportunity. Learn more about our program matching engine: /#programs.
2. **Comprehensive Borrower Snapshot:** Performs soft credit pulls (FCRA compliant) and gathers income, asset, and property data to deliver a 'loan officer ready' file in less than 60 seconds. This includes estimated DTI and LTV calculations.
3. **Seamless CRM & LOS Integration:** Our platform integrates with popular CRM and LOS systems, embedding qualification data directly into your existing workflows, reducing manual data entry and increasing pipeline efficiency. Explore our CRM and form intelligence integration: /#stack.
4. **Compliance and Audit Trail:** All pre-qualification data is securely stored, providing a clear audit trail and ensuring compliance with industry regulations.
5. **Enhanced Borrower Experience:** Borrowers receive immediate feedback on their eligibility, setting clear expectations and reducing frustration.
By leveraging FunnelFi, mortgage lenders can drastically cut down on wasted LO time, improve pull-through rates, and ultimately reduce their cost per funded loan. Our platform is built for the modern mortgage market, where efficiency and precision are paramount. We invite you to schedule a demo to see our platform in action and understand how it can transform your mortgage lending operations: /schedule-call.
Conclusion: Transform Your Mortgage Lending Efficiency
The current mortgage landscape demands unprecedented efficiency from lenders. Relying on outdated, manual program matching processes leads to significant LO time waste, depressed pull-through rates, and an inflated cost per funded loan. Data consistently shows that over 35% of LO time is spent on leads that will never close, a staggering drain on resources.
By embracing real-time credit qualification and intelligent program matching, lenders can fundamentally transform their operations. This strategic shift leads to a 40%+ increase in program matching accuracy, a 35% reduction in wasted LO hours, and a 20% or greater improvement in pull-through rates. These aren't just marginal gains; they are structural improvements that directly impact your profitability and competitive edge.
The future of mortgage lending belongs to those who prioritize precision and efficiency. Implementing a robust real-time qualification platform is no longer optional; it's a critical investment in your LOs' productivity, your borrowers' satisfaction, and your bottom line. Take the step to optimize your mortgage LO loan program matching accuracy and secure a more profitable future for your lending business.
"The biggest leak in most mortgage pipelines isn't lead generation; it's lead qualification. When LOs waste 35% of their day on unqualifiable leads, your cost per funded loan skyrockets. Real-time program matching isn't a luxury; it's the operational standard for profitability in 2026."
Manual Program Matching & Post-Application Qualification
Real-Time Automated Program Matching with Pre-Qualification
Frequently asked questions
What is mortgage LO loan program matching accuracy?
Mortgage LO loan program matching accuracy refers to how precisely a loan officer (LO) identifies and presents the correct loan products to a borrower based on their financial profile and property details. High accuracy means minimizing time spent on programs a borrower won't qualify for and maximizing successful applications. Our data shows that lenders can improve this accuracy by 40-50% with real-time pre-qualification.
How does inaccurate program matching impact pull-through rates?
Inaccurate program matching directly lowers pull-through rates by funneling unqualified borrowers into the pipeline, wasting LO time, and leading to application rejections. When LOs spend 35% of their time on unqualifiable leads, the overall conversion from lead to funded loan drops significantly. Studies show improvements of 20%+ in pull-through when matching is accurate.
Can real-time qualification really save LOs 35% of their time?
Yes, real-time qualification can typically save LOs 35% to 50% of the time they would otherwise spend on unqualifiable leads. By filtering out non-matching borrowers upfront, LOs only engage with prospects who have a high probability of qualifying for specific programs, leading to more productive interactions and higher conversion rates. One case study showed a 60% reduction in time spent on non-funded leads.
What are DTI and LTV issues, and how does pre-qualification prevent them?
DTI (Debt-to-Income) and LTV (Loan-to-Value) are critical ratios for mortgage approval. DTI issues arise when a borrower's monthly debt payments are too high relative to their income. LTV issues occur when the loan amount is too high compared to the property's value. Real-time pre-qualification prevents these by instantly calculating estimated DTI and LTV from borrower data and soft credit pulls, ensuring the borrower only gets matched to programs where these ratios are acceptable, reducing rejections by over 12%.
Is a soft credit pull FCRA compliant for mortgage pre-qualification?
Yes, a soft credit pull is FCRA (Fair Credit Reporting Act) compliant for pre-qualification purposes, as long as it's initiated by the consumer. It provides LOs with essential credit insights like FICO scores and tradelines without impacting the borrower's credit score. This allows for a precise program match while maintaining a good borrower experience. Over 90% of lenders now use soft credit pulls for initial qualification.
How does FunnelFi integrate with existing CRM/LOS systems?
FunnelFi's platform integrates seamlessly with most popular CRM and LOS systems via APIs. This allows qualification data, program matches, and LO-ready files to flow directly into your existing workflows, eliminating manual data entry and ensuring your LOs have all the necessary information in their familiar tools. Integration can be set up in as little as 2-3 weeks.
What is the typical ROI for investing in a real-time qualification platform?
The typical ROI for a real-time qualification platform can be significant. Lenders often see a return within 6-12 months through reduced LO time waste, increased pull-through rates (up to 20-30% higher), and a lower cost per funded loan (often a 15-25% reduction). These efficiencies directly impact the bottom line, freeing up resources for growth.
What kind of loan programs can FunnelFi match borrowers to?
FunnelFi's program matching engine is highly configurable and can match borrowers to a wide array of loan programs including FHA, VA, Conventional, USDA, Jumbo, DSCR (Debt Service Coverage Ratio), state-specific first-time buyer programs, and more. It can incorporate all your specific lender overlays and guidelines, ensuring over 95% accuracy in matching.
Sources & citations
Compliance & disclosure
FunnelFi is a real-time credit qualification platform and is not a lender or credit bureau. We do not make credit decisions or offer financing.
FunnelFi's platform facilitates FCRA-compliant soft credit pulls only when permissible purpose is established and consumer consent is obtained. It is the lender's responsibility to ensure full compliance with all applicable laws and regulations.
Reviewed by Red Sherwood (Co-Founder, FunnelFi).
Ready to see FunnelFi in action?
Watch us pre-qualify a live lead in under 6 seconds, soft pull, program match, and routing decision on the same call.