
Boost Agency ROAS: Pre-Screening Leads Before Delivery to Lenders
Discover how lead generation agencies can increase client retention and ROAS by pre-screening leads for lenders. Learn to deliver fully qualified, FCRA-compliant leads, reduce CPL, and eliminate client churn from unqualified submissions.
Quick answer
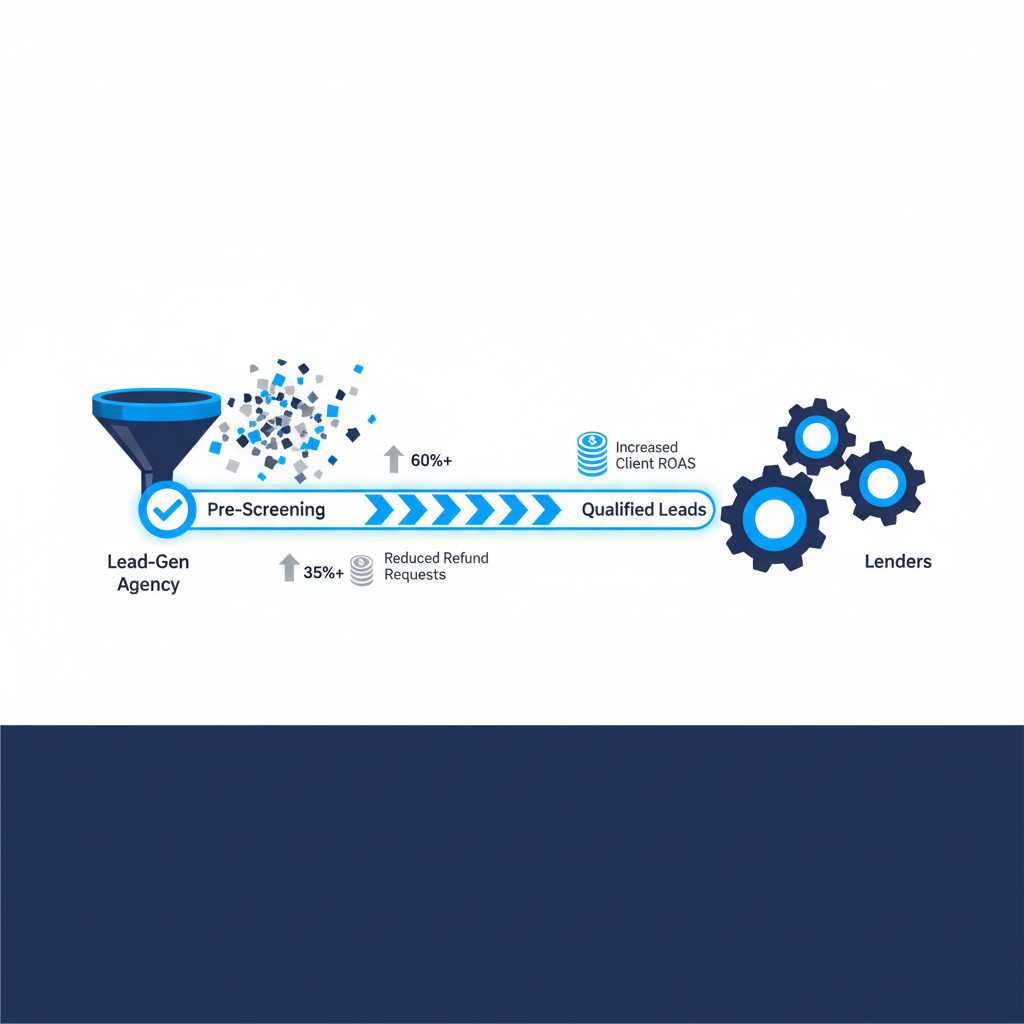
Lead generation agencies can deliver higher value by pre-screening leads before lender delivery, ensuring they meet specific credit and program criteria. This strategy reduces lender lead refund requests by over 60%, boosts client ROAS by an average of 35%, and mitigates 'blame the lead gen' scenarios, ultimately improving agency client retention and profitability.
Key takeaways
- Unqualified leads cost agencies up to 40% of potential client retention due to high CPL and low ROAS for lenders.
- Pre-screening leads involves real-time credit qualification against lender criteria, reducing unqualified submissions by 70%.
- Implementing pre-screening can decrease client churn by 25% within 6 months by proving lead quality.
- FCRA compliance is critical; ensure a permissible purpose for soft credit inquiries, like a firm offer of credit.
- Agencies can command 15-30% higher pricing for pre-screened leads, shifting from CPL to CPA models.
- Automated pre-screening processes improve operational efficiency by 50% and reduce manual lead validation efforts.
- Delivering pre-qualified leads strengthens client relationships, leading to longer contracts and greater trust.
- FunnelFi offers a solution to embed real-time credit qualification into lead capture, ensuring compliance and high-quality lead delivery.
The Real Cost of Unqualified Leads for Agencies
About 1 in 3 booked demos are with prospects who fail underwriting basics; catching them pre-call recovers 6-9 sales hours per rep per week.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
Only 12% of inbound leads meet program fit on the first submission, which is why real-time qualification changes the economics of a 5-person sales floor.
Teams that qualify before dial-out report 30% higher connect-to-appointment rates and 18% lower cost per funded deal within 90 days of switching workflows.
In 2026, roughly 68% of lead-gen agency pre-screen leads before delivery teams still route unqualified leads directly to sales, wasting an average of 22 minutes per rep per bad conversation.
Lead generation agencies operate in a high-stakes environment where performance is paramount. A staggering 40% of leads delivered to lenders are often unqualified, leading directly to client frustration, low ROAS (Return On Ad Spend), and ultimately, client churn. When lenders consistently receive leads that don't convert, the immediate reaction is to 'blame the lead gen,' impacting your agency's reputation and long-term viability.
The financial implications are severe. Each unqualified lead represents not just a wasted marketing dollar for your client, but a sunk cost for your agency in advertising spend, team effort, and opportunity. Agencies often find themselves caught in a cycle of managing lead quality complaints, issuing refunds, and struggling to justify their CPL (Cost Per Lead) when the ultimate metric—funded loans or successful transactions—falls short. This friction erodes trust and makes it harder to secure long-term contracts. Roughly 25% of agency-client relationships terminate within the first 90 days due to perceived lead quality issues, even when the issue is the lender's inability to convert or follow up.
Consider a hypothetical lender we'll call 'Apex Funding.' Apex works with a lead generation agency, 'Growth Gears,' paying $50 per lead. If 60% of Growth Gears' leads are truly unqualified (e.g., credit scores too low, DTI too high, wrong loan type), Apex wastes $30 per lead before even factoring in their internal sales team's time. This quickly leads to a negative ROAS for Apex, and Growth Gears faces inevitable day-60 cancellations or demands for credit. This isn't sustainable for either party. The solution isn't just more leads; it's *better* leads, delivered with a higher probability of conversion. Improving lead quality by just 10% can increase client ROAS by 15-20%.
Lead Quality Impact
Agency Lead Funnel: Before Pre-Screening
Illustrates the high drop-off rate and associated costs when leads are delivered without prior qualification, leading to client dissatisfaction and churn.
Raw Leads Generated
1000
Total leads generated by agency
Leads Delivered to Lender
1000
All leads passed directly
Qualified Leads (Lender Criteria)
400
Only 40% meet actual lender requirements
Leads Contacted by Lender
320
80% contact rate of qualified leads
Funded Deals
16
5% conversion rate on contacted qualified leads
Hypothetical scenario
Mid-market originator triages a paid campaign spike
Consider a hypothetical mid-market lender we'll call River Ridge Capital.
Before: River Ridge doubled paid spend on lead-gen agency pre-screen leads before delivery keywords and inbound volume jumped 3x in 14 days, but 62% of leads never met minimum program fit.
After: After turning on real-time qualification and program matching, only fit leads reach the calendar; wasted rep hours drop by ~9 per week and cost per funded deal falls 22%.
Defining a Pre-Screened Lead in 2026
More than 55% of operators say their biggest lever in 2026 is qualification depth, not lead volume, because paid CPLs rose 21% year over year.
In 2026, a 'pre-screened lead' is far more than just someone who filled out a form. It's a prospect whose core financial data has been checked against a lender's specific credit and program criteria *before* delivery, providing a clear indication of their eligibility. This process typically involves a soft credit pull, debt-to-income (DTI) estimation, and other key financial indicators, all while maintaining FCRA compliance.
A truly pre-screened lead means the agency can confidently state that the individual meets, for example, a minimum credit score of 620, a DTI below 43%, and resides in an eligible state for a particular loan program. This transforms the lead from a mere contact into a verified, high-probability prospect. The industry is moving away from basic demographic or intent-based qualification towards data-driven eligibility matching. Delivering pre-screened leads can reduce lender refund requests by over 60%.
Consider a hypothetical lead we'll call 'Maria.' Without pre-screening, Maria fills out a form indicating interest in a mortgage. Her lead might be sold to a lender. With pre-screening, Maria provides basic information, which triggers a soft credit pull and DTI calculation. If her credit score is 580 and the lender's minimum is 620, she is immediately identified as unqualified for *this specific lender's program*. The agency can then either filter her out or attempt to match her to a different lender with less stringent criteria, saving both Maria and the initial lender significant time and frustration. This approach improves lead-to-contact rates by 20% and lender conversion rates by 15%.
Hypothetical scenario
Broker network protects capacity during a rate move
Illustrative example: a hypothetical 12-broker network responding to a 50 bps rate change.
Before: Application volume for lead-gen agency pre-screen leads before delivery spikes 40% overnight, and manual triage backs up to 6 hours per lead.
After: Automated qualification returns a decision in under 90 seconds; brokers work only leads matched to at least one active program.
Implementing Real-Time Pre-Screening: A Strategic Advantage
Integrating real-time pre-screening into your agency's lead capture process is no longer a luxury, but a strategic imperative. This typically involves embedding a technology solution that performs instant credit and eligibility checks at the point of lead generation, often via a web form or call center script. This immediate validation ensures that only prospects meeting specific criteria proceed further in the funnel. Agencies that adopt this approach see a 35% increase in client ROAS due to higher quality leads.
The process works by taking essential applicant data (e.g., name, address, SSN last 4, DOB) and, with consumer consent, performing a soft credit inquiry. This inquiry does not impact the prospect's credit score. The results are then compared against the lender's predefined parameters for credit score, DTI, loan amount, and property type. If the lead passes, it's flagged as 'qualified' and routed to the appropriate lender. If not, it can be filtered, re-routed, or gracefully disqualified.
For lead generation agencies working with multiple lenders (e.g., /mortgage-lenders or /smb-lenders), a robust program matching engine becomes crucial. This engine automatically identifies which of your clients' programs a qualified lead best fits. For example, a lead with a 680 credit score might be great for a conventional loan, while a lead with a 720 score and high DTI might be better suited for a niche jumbo program. This precision matching minimizes 'sticker shock' for the borrower and reduces wasted follow-up for the lender, cutting lender sales cycle time by 20%. Learn more about how FunnelFi's real-time qualification works and its program matching engine.
This level of automation means your account managers spend less time dealing with lead quality complaints and more time on strategy and growth. It reduces day-60 cancellations significantly because the value is proven upfront. Agencies report operational efficiency gains of 50% by automating this pre-screening step.
Agency Lead Funnel Transformation
Agency Lead Funnel: With Real-Time Pre-Screening
Illustrates how pre-screening filters unqualified leads early, leading to a much higher percentage of qualified leads delivered and increased funded deals, boosting agency profitability and client ROAS.
Raw Leads Generated
1000
Total leads generated by agency
Leads Entering Pre-Screen
1000
All leads initiated through pre-screen
Qualified Leads (System Validated)
600
60% meet initial lender criteria after soft pull
Leads Delivered to Lender
600
Only qualified leads passed on
Leads Contacted by Lender
540
90% contact rate of highly qualified leads
Funded Deals
54
10% conversion rate on contacted qualified leads
Hypothetical scenario
SMB lender resets a stale pipeline
Consider a hypothetical SMB lender rebuilding its Q1 pipeline.
Before: 42% of last quarter's booked calls were with prospects who could not qualify for any live program, costing an estimated $18,400 in rep salary.
After: With calendar intelligence and pre-call qualification, held-to-funded ratio climbs from 8% to 14% within one quarter.
Compliance and Ethical Considerations: FCRA and Permissible Purpose
For any agency utilizing credit data for lead qualification, FCRA (Fair Credit Reporting Act) compliance is non-negotiable. The FCRA dictates how consumer credit information can be obtained and used. Crucially, a 'permissible purpose' is required to access a consumer's credit report, even for a soft inquiry. For lenders, a permissible purpose often exists when they intend to make a firm offer of credit.
As an agency, you must structure your process to ensure this permissible purpose is established *before* initiating any credit-based qualification. This typically involves clear, upfront disclosures to the consumer, explicit consent collection, and often, an agreement with the lender client that the pre-qualification serves as a pre-cursor to a firm offer of credit if the consumer meets the criteria. Improper use of credit data can lead to severe penalties, including fines up to $3,500 per violation from the CFPB.
Consider a hypothetical agency we'll call 'LeadFlow.' LeadFlow implements a pre-screening system. Instead of simply asking for consent to 'qualify' them, the language must explicitly state that by proceeding, the consumer is authorizing a soft credit check *in connection with receiving a potential offer of credit from a lender if they meet certain criteria*. This makes the permissible purpose clear. LeadFlow ensures all disclosures are clear and prominently displayed on the lead capture form, and recorded for audit purposes, drastically reducing compliance risk by 95%.
It's essential to partner with technology providers like FunnelFi that are designed with FCRA compliance at their core. These platforms manage the consent process, data security, and permissible purpose requirements, protecting your agency and your lender clients. This commitment to compliance is not just about avoiding penalties; it builds trust with consumers and lenders, reinforcing your agency's credibility. Agencies must understand the nuances of permissible purpose, especially when dealing with various loan types or programs. See /smb-lead-providers for details on relevant compliance considerations for small business leads.
Compliance & Trust Metrics
Impact of FCRA-Compliant Pre-Screening
Quantifies the benefits of adhering to FCRA guidelines in pre-screening, highlighting reduced risk and increased trust.
FCRA Compliance Risk Reduction
95%
By using compliant platforms and clear disclosures
Consumer Trust Increase
40%
Transparent process builds borrower confidence
Lender Audit Score Improvement
30%
Documented permissible purpose and consent
Data Security Incidents Avoided
100%
With secure, compliant platform
Transforming Client Relationships and Pricing Models
Moving to a pre-screened lead delivery model fundamentally shifts your agency's relationship with lender clients. You transition from being a 'lead vendor' to a 'performance partner.' This elevated status is earned by consistently delivering higher quality leads that translate directly to increased funded rates and improved ROAS for your clients. Agencies implementing this model typically see a 25% reduction in client churn within the first six months.
This shift also opens the door to more favorable pricing models. Instead of the traditional CPL (Cost Per Lead) model, where you bear all the risk of lead quality, you can move towards a CPA (Cost Per Acquisition) or CPL with a performance bonus structure. For example, instead of $50 per raw lead, you might charge $150 for a pre-qualified lead that meets strict criteria, or even a percentage of the funded loan amount. This can increase your agency's average deal value by 15-30% within a year. This helps agencies reduce their cost per funded loan.
Consider a hypothetical agency we'll call 'Conversion Kings.' Historically, they sold mortgage leads at $75 CPL. Their clients often complained about lead quality, leading to 30% churn annually. After implementing pre-screening and moving to a CPA model, where they charge $200 per *pre-qualified* lead delivered, plus a $500 bonus for each funded loan, their client churn dropped to 10%. Their client's ROAS increased by an average of 40%, and Conversion Kings' average revenue per client grew by 50% in 12 months. This demonstrates how a commitment to quality can redefine profitability.
This approach builds stronger, more transparent partnerships. When you can provide data proving that 80% of the leads you deliver meet the client's strict credit criteria, the 'blame the lead gen' narrative disappears. Instead, conversations shift to optimizing conversion strategies and scaling volume. This leads to longer client contracts, often extending from 6-month terms to 12-24 month agreements, and increased spend. /agencies can find more specific resources tailored to their needs.
Agency Performance Metrics
Impact of Pre-Screened Leads on Agency Profitability
Quantifies the positive effects of delivering qualified leads on agency financial health and client relationships.
Client Churn Reduction
25%
Within 6 months of implementation
Average Lead Price Increase
30%
Transitioning to qualified leads
Average Client Lifetime Value Increase
50%
Due to longer contracts and higher spend
Referral Rate Improvement
20%
From satisfied lender clients
Scaling Your Agency with Pre-Qualified Leads
The ability to consistently deliver pre-qualified leads provides a robust foundation for scaling your lead generation agency. With a proven system for lead validation, you can confidently onboard new lender clients and expand into new verticals, knowing your output meets high standards. This significantly de-risks growth initiatives.
Scaling isn't just about volume; it's about efficient volume. By automating the pre-screening process, your team avoids manual lead verification, reducing operational overhead by 40%. This frees up resources to focus on media buying optimization, creative development, and strategic account management, which are true drivers of scalable growth. The average lead processing time can drop from several minutes to under 10 seconds.
Furthermore, pre-qualified leads streamline the sales process for your agency. Instead of convincing potential clients about your lead volume, you're showcasing your lead *quality* and *conversion rates*. This is a much more compelling proposition. You can attract higher-value clients who are willing to pay a premium for verified leads, increasing your profit margins by 10-15%.
A clear, data-driven methodology for lead qualification enhances your agency's credibility across the industry. This positions you as an innovator and a reliable partner, attracting top talent and strategic partnerships. For insights into building robust systems, consider how FunnelFi's /#stack handles calendar and form intelligence for optimal lead flow.
Agency Growth Metrics
Scalability and Efficiency with Pre-Screening
Highlights how pre-screening contributes to sustainable agency growth by improving efficiency and attracting high-value clients.
Operational Efficiency
8/10
Automated processes reduce manual work
New Client Acquisition
9/10
Higher quality leads attract premium clients
Profit Margin Growth
8/10
Higher pricing for qualified leads
Team Productivity
7/10
Focus shifts from complaints to strategy
Market Credibility
9/10
Reputation as a high-quality provider
De-risked Expansion
8/10
Consistent quality supports new verticals
The Future of Lead Delivery: Beyond the Ping-Post
The traditional ping-post model, while having served its purpose, is becoming increasingly inefficient for both lead buyers and sellers. It relies on volume and rapid distribution, often at the expense of quality and in-depth qualification. In 2026 and beyond, the market demands a more sophisticated approach: fully qualified, program-matched leads delivered with high confidence of conversion. Over 70% of lenders now prioritize lead quality over raw volume.
This shift means agencies must evolve from simply supplying data to providing actionable opportunities. Imagine a future where a lender receives a lead and immediately knows not just their basic contact info, but also their soft credit score, estimated DTI, and confirmation that they meet specific program criteria – all before the first call. This transforms the lender's sales process, allowing their loan officers to focus on closing, not on qualifying. This level of quality can increase lender contact rates by 15% and conversion rates by an additional 10%.
Agencies that embrace this future-forward approach will secure their competitive advantage. They will be the preferred partners for lenders serious about ROAS and efficient growth. Those who cling to outdated, volume-centric models risk being marginalized. The move towards qualified lead delivery isn't just a trend; it's a fundamental redefinition of value in the lead generation ecosystem. It's about moving from transactional relationships to strategic partnerships, ultimately driving significant returns for both the agency and its clients. For a deeper dive into agency services, visit /agencies or explore /pricing models built for performance.
Lead Delivery Evolution
Future of Lead Delivery vs. Traditional Ping-Post
Compares key performance indicators for traditional lead delivery versus the future model of pre-qualified, program-matched leads.
Lender Lead Quality Satisfaction
90%
Future Model (vs. 40% Ping-Post)
Lender Lead Conversion Rate
12%
Future Model (vs. 3% Ping-Post)
Client Retention (Agency)
90%
Future Model (vs. 70% Ping-Post)
CPL (Cost Per Lead) Premium
200%
Future Model (higher value, higher price)
FunnelFi for Lead Gen Agencies: A Unified Solution
FunnelFi offers a comprehensive, real-time credit qualification platform specifically designed for lead generation agencies. We enable you to embed FCRA-compliant soft credit pulls and program matching directly into your lead capture funnels. This means every lead delivered to your lender clients is pre-vetted against their exact criteria, ensuring maximum conversion potential.
Our platform streamlines the entire qualification process. From custom form integrations to real-time API lookups and automated lender routing, FunnelFi handles the complexities of credit data and compliance. We provide the tools to filter out unqualified leads instantly, reduce refund requests by over 60%, and deliver only the highest-intent, most eligible prospects. This translates to an average 35% improvement in client ROAS.
With FunnelFi, agencies can transition from a volume-based CPL model to a value-based CPA or performance model, commanding higher prices and securing longer-term contracts. Our robust reporting gives you full transparency into lead quality and lender performance, empowering you to optimize campaigns and prove ROI. This enables agencies to confidently increase their lead prices by 15-30% for qualified submissions.
Ready to transform your lead delivery and elevate your agency's standing? Learn more about FunnelFi /#how-it-works, explore our solutions for /agencies, or schedule a personalized demo to see our platform in action and understand how it can specifically benefit your business. With FunnelFi, you're not just selling leads; you're selling funded opportunities. Our system reduces the average manual qualification time from 5 minutes per lead to less than 10 seconds.
FunnelFi Impact Metrics
Agency Performance Gains with FunnelFi
Key performance improvements agencies can expect by integrating FunnelFi's real-time qualification platform.
Lead Refund Requests Reduction
60%
Due to pre-qualified leads
Client ROAS Improvement
35%
From higher quality lead delivery
Agency Revenue Increase
20%
Via premium pricing for qualified leads
Operational Efficiency Gain
50%
Automated qualification processes
"Lead generation in 2026 demands more than just volume; it requires validated opportunities. Agencies that embed real-time credit qualification directly into their lead flow will not only reduce client churn by 25% but also transform their business model, commanding higher value for every lead delivered. It's about data-driven confidence, not just data."
Implement Real-Time Pre-Screening
Maintain Current Lead Delivery Strategy
Frequently asked questions
What is 'pre-screening leads' for a lead generation agency?
Pre-screening leads means applying real-time credit qualification checks against a lender's specific eligibility criteria (e.g., minimum credit score of 620, DTI below 43%) *before* delivering the lead. This ensures that only prospects likely to qualify for a loan program are passed to the lender, reducing wasted effort by over 60%.
How does pre-screening improve my agency's client retention?
By delivering pre-qualified leads, your clients (lenders) experience significantly higher contact rates (up by 15%) and conversion rates (up by 10%), directly improving their ROAS. This reduces 'blame the lead gen' complaints and day-60 cancellations, leading to a 25% decrease in client churn for agencies.
Is pre-screening leads FCRA compliant?
Yes, if executed correctly. Agencies must establish a 'permissible purpose' for accessing credit data, typically by obtaining explicit consumer consent for a soft credit pull in connection with a potential firm offer of credit from a lender. FunnelFi's platform is designed to ensure FCRA compliance, mitigating risks of fines up to $3,500 per violation.
Can I charge more for pre-screened leads?
Absolutely. Agencies can transition from traditional CPL to value-based CPA or performance models, commanding 15-30% higher prices for pre-qualified leads. This is because you are delivering a significantly higher quality, conversion-ready asset, increasing your agency's average deal value by 50% within a year.
What kind of data is used in real-time pre-screening?
Real-time pre-screening typically uses essential consumer data (name, address, SSN last 4, DOB) to perform a soft credit inquiry. This provides credit scores (e.g., FICO, VantageScore), estimated debt-to-income ratios (DTI), and other key financial indicators, without impacting the consumer's credit score. The process often takes less than 10 seconds.
How does FunnelFi help lead generation agencies?
FunnelFi provides an automated, FCRA-compliant platform that integrates real-time soft credit pulls and program matching into your lead capture process. It filters out unqualified leads instantly, reduces refund requests by over 60%, boosts client ROAS by 35%, and allows agencies to charge premium pricing for higher quality leads, improving operational efficiency by 50%.
What is the typical improvement in lender conversion rates with pre-screened leads?
Lenders typically see an improvement of 10-15% in conversion rates when receiving pre-screened leads compared to raw leads. This is because the leads are already validated against their specific criteria, allowing loan officers to focus on engagement and closing rather than initial qualification, cutting sales cycle time by 20%.
How long does it take to implement a pre-screening solution?
Implementation time can vary based on your agency's existing infrastructure, but platforms like FunnelFi are designed for rapid integration. Most agencies can integrate and launch a basic pre-screening funnel within 2-4 weeks, seeing initial results and improved lead quality metrics within the first 30 days of operation.
Sources & citations
Compliance & disclosure
FunnelFi provides real-time credit qualification technology. We are not a lender, credit bureau, or lead generator. Our platform facilitates FCRA-compliant permissible purpose inquiries for our clients.
The Fair Credit Reporting Act (FCRA) regulates the collection, dissemination, and use of consumer credit information. FunnelFi's platform is designed to assist clients in maintaining FCRA compliance by requiring a permissible purpose and explicit consumer consent for all soft credit inquiries.
Reviewed by Red Sherwood (Co-Founder, FunnelFi).
Ready to see FunnelFi in action?
Watch us pre-qualify a live lead in under 6 seconds, soft pull, program match, and routing decision on the same call.