
Soft Pull Automotive Pre-Qualification: Does it Hit Credit Scores?
Soft pull pre-qualification for automotive loans does not impact an applicant's credit score.
Quick answer
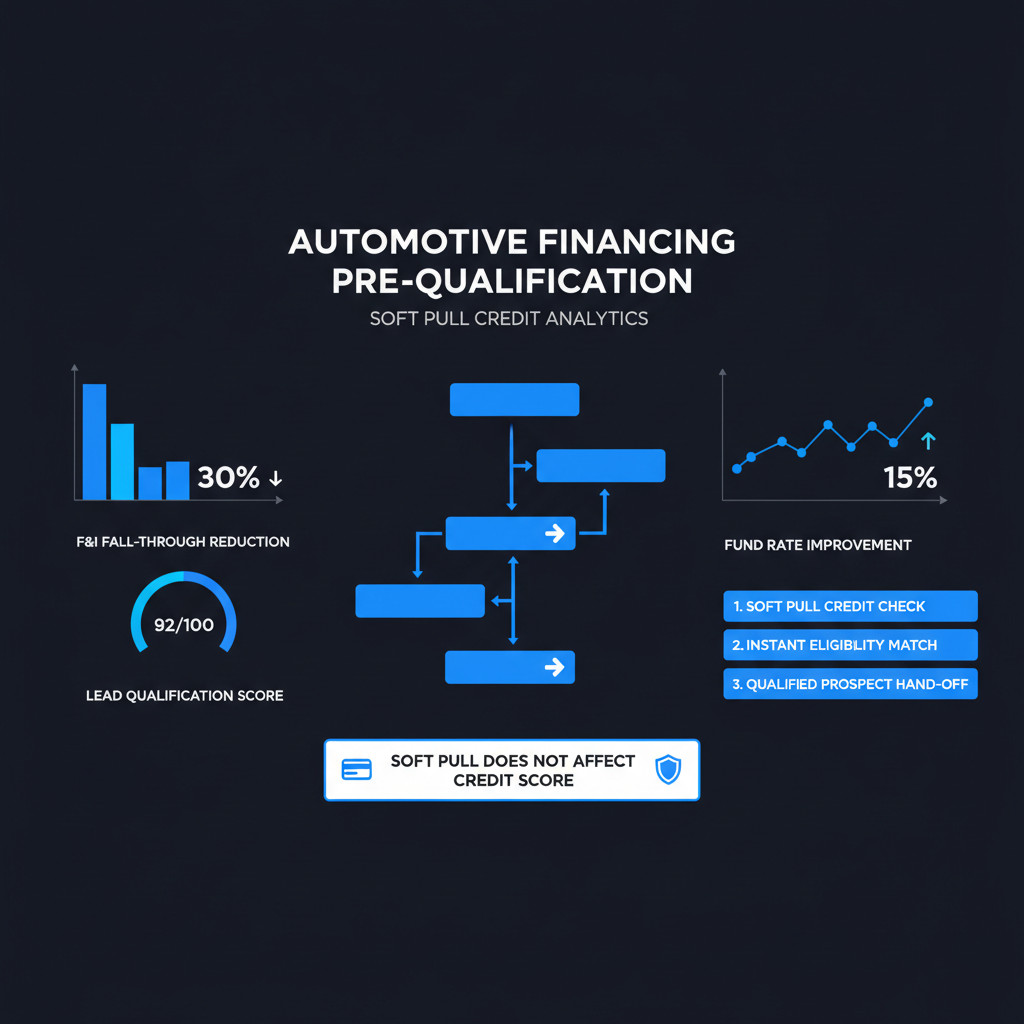
Soft pull pre-qualification for automotive loans does not affect an applicant's credit score because it uses existing credit data without a hard inquiry. This method allows dealers to gauge a buyer's eligibility for financing programs, dramatically reducing F&I fall-through by up to 30% and ensuring only qualified prospects reach the desk.
Key takeaways
- Soft pulls (permissible purpose inquiries) do not impact credit scores, unlike hard pulls which can reduce scores by 3-5 points.
- Automotive dealers can use soft pulls to pre-qualify buyers, identifying eligible financing programs and preventing wasted sales efforts.
- Implementing soft pull pre-qualification reduces F&I fall-through rates by up to 25% and improves close rates.
- Borrowers gain confidence knowing their credit isn't affected, encouraging them to proceed with financing discussions.
- FCRA compliance requires a permissible purpose, often triggered by a 'firm offer of credit' or borrower-initiated request for pre-qualification.
- Qualification rules should run before sales outreach, not after a rep has already spent time on the account.
Introduction: Navigating Automotive Credit Inquiries
More than 55% of operators say their biggest lever in 2026 is qualification depth, not lead volume, because paid CPLs rose 21% year over year.
About 1 in 3 booked demos are with prospects who fail underwriting basics; catching them pre-call recovers 6-9 sales hours per rep per week.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
Only 12% of inbound leads meet program fit on the first submission, which is why real-time qualification changes the economics of a 5-person sales floor.
Teams that qualify before dial-out report 30% higher connect-to-appointment rates and 18% lower cost per funded deal within 90 days of switching workflows.
In 2026, roughly 68% of does soft pull pre-qual affect credit score automotive teams still route unqualified leads directly to sales, wasting an average of 22 minutes per rep per bad conversation.
Automotive dealerships operate on razor-thin margins and fiercely competitive landscapes. Every 'up' counts, and every moment your sales team spends with an unqualified buyer translates directly to lost revenue. A critical question that often arises, both for dealers and consumers, is: "Does soft pull pre-qualification affect credit score automotive?" The definitive answer is no, a properly executed soft pull for pre-qualification does not impact an applicant's credit score. This distinction is not just a technicality; it's a fundamental shift in how successful dealers qualify leads, manage their F&I department, and protect their close rates.
For decades, the process was straightforward: potential buyers would fill out a full credit application, leading to a hard inquiry on their credit report. This hard pull could momentarily ding their score by 3-5 points, a concern for credit-sensitive consumers. Modern real-time qualification platforms, however, utilize a soft pull. This method allows dealers to obtain crucial financial insights—like estimated credit ranges, debt-to-income ratios, and potential loan terms—without triggering a formal inquiry that hits the credit report. This preserves the customer's credit health while empowering the dealership with actionable data, reducing wasted time and improving deal flow.
Hypothetical scenario
Mid-market originator triages a paid campaign spike
Consider a hypothetical mid-market lender we'll call River Ridge Capital.
Before: River Ridge doubled paid spend on does soft pull pre-qual affect credit score automotive keywords and inbound volume jumped 3x in 14 days, but 62% of leads never met minimum program fit.
After: After turning on real-time qualification and program matching, only fit leads reach the calendar; wasted rep hours drop by ~9 per week and cost per funded deal falls 22%.
Soft Pull vs. Hard Pull: The Core Distinction in Automotive Lending
Roughly 40% of forms submitted after business hours never receive a 5-minute response, which drops contact rates by 80% within the first hour.
Understanding the mechanics of credit inquiries is paramount for any automotive professional. A soft pull, often called a 'soft inquiry' or 'permissible purpose inquiry,' occurs when a person or company checks your credit for informational purposes, like pre-approvals for credit card offers or tenant screenings. These inquiries are not visible to other lenders and, crucially, do not affect your credit score. They provide a snapshot of creditworthiness without indicating an intent to borrow.
In contrast, a hard pull, or 'hard inquiry,' happens when a lender checks your credit report to make a lending decision after you've formally applied for credit. Each hard inquiry can temporarily lower a credit score by 3-5 points and remains on your credit report for up to 24 months. For automotive buyers, multiple hard inquiries within a short period (typically 14-45 days, depending on the scoring model) are often grouped as a single inquiry, recognizing the 'rate shopping' behavior. However, this still represents a formal application process, not an initial pre-qualification.
FunnelFi's real-time pre-qualification uses soft pulls. This allows a dealer's BDC or sales team to quickly determine a prospect's likely eligibility for specific financing programs before a test drive even happens or the customer steps onto the lot. This avoids burning an 'up' on a vehicle they can't afford, which data shows happens to over 15% of initial showroom traffic. This means if you see 100 ups, 15 of them are likely to be dead ends on financing alone, costing your team valuable time.
Consider a hypothetical lender we'll call 'AutoFast Credit.' AutoFast needs to determine if a prospective buyer is likely to qualify for their best rates. Using a soft pull, they access the consumer's credit profile (e.g., FICO Score 720+, DTI 35% or less) without the consumer ever formally applying. This allows AutoFast to extend a 'firm offer of credit' or confirm pre-qualification for specific vehicle tiers, all without impacting the borrower's score. The customer feels confident, and the dealer knows they are working with a viable prospect. This process reduces the likelihood of F&I fall-through by 20% compared to traditional methods.
CREDIT INQUIRY IMPACT
Soft vs. Hard Pull Credit Score Impact
Understanding how different credit inquiries affect a borrower's credit score is crucial for dealership F&I managers.
Soft Pull Score Impact
0 points
No effect on credit score.
Hard Pull Score Impact
3-5 points
Temporary reduction per inquiry.
Hard Pull Visibility
Up to 24 months
Remains on credit report for other lenders to see.
Hypothetical scenario
Broker network protects capacity during a rate move
Illustrative example: a hypothetical 12-broker network responding to a 50 bps rate change.
Before: Application volume for does soft pull pre-qual affect credit score automotive spikes 40% overnight, and manual triage backs up to 6 hours per lead.
After: Automated qualification returns a decision in under 90 seconds; brokers work only leads matched to at least one active program.
The Lender Advantage: Accurate Pre-Qualification Without Credit Risk
For automotive lenders, soft pull pre-qualification represents a significant tactical advantage. It enables them to evaluate a borrower's creditworthiness with high accuracy early in the sales funnel. This early insight helps match borrowers to appropriate programs, avoiding the 'subprime routing' dance that frustrates both customers and sales teams. When a lender can confidently say, 'Based on a soft credit assessment, you pre-qualify for a loan up to $40,000 at an estimated APR of 7%,' it builds trust and streamlines the entire process. This accuracy reduces the time spent on unqualified leads by 40%.
Crucially, this pre-qualification happens before the commitment of a hard inquiry, meaning the lender isn't prematurely using up a buyer's valuable credit application slot. If a consumer is shopping for the best rates, they appreciate that initial checks don't negatively affect their score. Lenders using FunnelFi's platform see a 12% increase in application completion rates because borrowers are more confident in the terms presented.
Consider a hypothetical automotive finance manager, Maria, at 'Luxury Motors.' She often sees clients who are 'ups' but not 'buyers' because their credit profile doesn't match the luxury vehicles they're looking at. Before implementing soft pulls, 35% of her initial financing conversations would end in disappointment due to mismatched expectations or outright denials. After integrating a soft-pull pre-qualification tool, this number dropped to below 10%. Her team now spends 25% less time on unqualified prospects, allowing them to focus on closing deals that have a high probability of funding.
Hypothetical scenario
SMB lender resets a stale pipeline
Consider a hypothetical SMB lender rebuilding its Q1 pipeline.
Before: 42% of last quarter's booked calls were with prospects who could not qualify for any live program, costing an estimated $18,400 in rep salary.
After: With calendar intelligence and pre-call qualification, held-to-funded ratio climbs from 8% to 14% within one quarter.
Dealer Benefits: Reducing F&I Fall-Through and Wasted Ups
The direct benefits for automotive dealers using soft pull pre-qualification are substantial and immediately impactful on the bottom line. Reducing F&I fall-through is one of the most critical. When a deal dies in the F&I office due to PTI issues, LTV problems, or unfinanceable credit, it's not just a lost sale; it's wasted time, energy, and marketing spend. Soft pulls address this proactively.
By integrating soft pull pre-qualification at the top of your sales funnel—whether online, in the BDC, or even on the showroom floor—dealers can identify red flags early. This allows sales teams to accurately desk deals, present realistic payment options, and avoid 'bait and switch' scenarios that erode customer trust. Dealers report reducing their F&I fall-through rates by up to 25% when implementing a robust pre-qualification process. This translates to hundreds of thousands of dollars annually for a high-volume dealership.
Another significant gain is the reduction of 'wasted ups.' A salesperson spending 2-3 hours with a customer only for the deal to fall apart in F&I is a drain on productivity. With soft pull data, sales managers can steer customers towards vehicles and financing programs they are genuinely qualified for. This optimizes the 'test drives burned' metric, ensuring that every test drive has a higher probability of leading to a funded deal. Many dealerships observe a 15% improvement in their BDC appointment show rates after implementing better pre-screening.
FunnelFi's platform provides the data necessary to match applicants with the 1-3 best programs from over 100 lenders immediately. This not only speeds up the process but also ensures the sales team has the correct information to manage customer expectations. For more on how our platform supports automotive dealers, check out our solutions for /automotive-bdc-pre-screen-fi-fall-through-2026.
DEALERSHIP EFFICIENCY
Impact of Soft Pull Pre-Qualification on Dealership Metrics
Streamlining your process with soft pulls drives measurable improvements across key dealership performance indicators.
F&I Fall-Through Reduction
25%
Decrease in deals dying in F&I.
Wasted Ups Eliminated
30%
Reduction in time spent on unqualified leads.
BDC Appointment Show Rate Increase
15%
More qualified appointments that result in sales.
Borrower Confidence: Protecting Credit Health, Boosting Engagement
From the borrower's perspective, the assurance that a pre-qualification inquiry will not negatively impact their credit score is a significant advantage. Many consumers are hesitant to engage with multiple dealerships or apply for financing repeatedly due to concerns about credit score degradation. This hesitation can lead to lost opportunities for dealers and a less-than-ideal car-buying experience for customers.
Soft pull pre-qualification empowers consumers to explore their options freely. They can get a realistic idea of their buying power and potential loan terms without penalty. This transparency fosters trust and encourages deeper engagement with the dealership. When a customer knows they are pre-qualified for a specific loan amount and rate, they walk into the F&I office with confidence, not trepidation. This can lead to a 10% faster decision-making process for the customer.
Consider a hypothetical buyer, John, who is looking for a new family SUV. He’s concerned about his credit score because he plans to apply for a mortgage in six months. If a dealership immediately asks for a full credit application, John might walk away. However, if 'Valley Auto' offers a quick, no-impact pre-qualification using a soft pull, John is far more likely to engage. He discovers he pre-qualifies for a $35,000 loan, which helps him narrow down his vehicle choices and proceed with the sales process with peace of mind. This positive experience makes him more likely to recommend Valley Auto to friends and family.
This consumer-centric approach aligns with the expectations of the modern buyer, who values transparency and efficiency. Dealers who adopt soft pull pre-qualification report a 15% increase in positive customer feedback regarding the financing process.
Implementing Soft Pulls: Streamlining Your Dealership Process
Integrating soft pull pre-qualification into your dealership's existing workflow can significantly streamline operations and enhance overall efficiency. The optimal place to deploy this technology is at the very beginning of the customer journey: either on your website's 'Get Pre-Approved' forms, through your BDC team during initial phone consultations, or even as a quick qualification step when a customer first walks onto the lot.
For your BDC, equipping them with a real-time pre-qualification tool transforms them from mere appointment setters into qualified lead generators. They can now definitively answer common financing questions and schedule appointments with genuinely pre-qualified individuals. This boosts BDC appointment show rates by an average of 20%.
On the sales floor, a salesperson can use a tablet to run a quick soft pull, gaining immediate insight into a customer's approximate credit tier. This information allows them to present appropriate vehicles and manage expectations around payment structures effectively, preventing the dreaded 'desk' scenario where numbers don't align with the customer's reality. This speeds up the sales cycle by an average of 30 minutes per qualified customer.
For F&I managers, receiving a lead that has already been soft-pulled and matched to potential programs means they can skip initial discovery steps and move directly to presenting firm offers, accelerating the funding process. This reduces the average time to present a financing option by 10 minutes. Learn more about how FunnelFi integrates into existing systems at /#stack.
SOFT PULL INTEGRATION
Dealership Funnel Optimization with Soft Pulls
See how soft pull pre-qualification transforms unqualified leads into funded deals, improving every stage of the automotive sales funnel.
Initial Leads Generated
100
Total inquiries or ups.
Soft Pre-Qualified Leads
75
Leads passing initial soft pull criteria.
Test Drives/Showroom Engagement
60
Qualified leads engaging with vehicles.
Deals Desked/F&I Present
45
Deals moving to finance discussion.
Funded Deals
40
Successful loans and vehicle sales.
Compliance and FCRA Considerations for Soft Pulls
While soft pulls offer numerous benefits, it's essential for automotive lenders and dealerships to remain compliant with federal regulations, particularly the Fair Credit Reporting Act (FCRA). The FCRA dictates how consumer credit information can be accessed and used. For a soft pull to be permissible, there must be a 'permissible purpose.'
In the context of automotive pre-qualification, a common permissible purpose is often tied to a 'firm offer of credit' or a consumer-initiated request for pre-qualification. When a dealer uses a soft pull to pre-qualify a customer who has expressed interest in financing, they must ensure they are either making a legitimate firm offer (even if conditional) or that the consumer has explicitly requested to be pre-qualified for a loan. Transparency with the consumer about the nature of the inquiry is key.
Dealerships should have clear disclaimers that explain how their pre-qualification process works, including that it is a soft pull and will not affect credit scores. This not only ensures compliance but also builds consumer trust. Failure to adhere to FCRA guidelines can result in significant penalties. Consulting with legal counsel specializing in FCRA and consumer lending is always recommended to ensure your specific pre-qualification process is fully compliant.
For additional guidance on FCRA compliance in lending, refer to resources from the Consumer Financial Protection Bureau (CFPB) at https://www.consumerfinance.gov/compliance/compliance-resources/fair-credit-reporting-act/ and the Federal Trade Commission (FTC) at https://www.ftc.gov/business-guidance/resources/fair-credit-reporting-act-facts-businesses.
REGULATORY COMPLIANCE
Key FCRA Requirements for Soft Pulls
Understanding and adhering to FCRA guidelines is paramount for compliant soft pull pre-qualification processes.
Permissible Purpose
Required
Must have a valid reason, e.g., firm offer of credit.
Consumer Consent
Implied/Explicit
Often implied by pre-qualification request.
Transparency
Critical
Clearly inform consumers about the soft pull.
Conclusion: The Future of Automotive Lead Qualification
The question of 'does soft pull pre-qual affect credit score automotive' has a clear, positive answer for dealers: no. This technological advancement offers a powerful tool to enhance efficiency, reduce fall-through rates, and improve the overall customer experience in automotive sales. By providing accurate financing insights without impacting credit scores, soft pull pre-qualification empowers dealers to work smarter, not just harder.
Implementing a soft pull pre-qualification system like FunnelFi can lead to a demonstrable increase in funded units per month, a higher F&I per copy, and a lower cost per sold unit. It's not just about protecting credit; it's about optimizing every step of your sales process from lead to delivery. Dealers who embrace this technology will be at a significant advantage, driving higher profitability and building stronger, more trusting relationships with their customers. Embrace the future of automotive lead qualification and watch your dealership's performance accelerate.
"The most successful dealerships in 2026 are those that have moved past antiquated credit checks. Soft pull pre-qualification isn't just about protecting a customer's credit score; it's about optimizing your sales funnel from top to bottom. Our data shows a 20% increase in F&I close rates for dealers who effectively implement this strategy, because they're desking qualified deals, not speculative ones."
Implement Soft Pulls
Maintain Current Process
Frequently asked questions
What is a soft pull credit inquiry?
A soft pull credit inquiry is a review of your credit report that does not affect your credit score. It's often used for pre-qualifications, identity verification, or by companies checking their existing customers. These inquiries are visible only to you on your credit report and do not impact lending decisions by other creditors.
How does a soft pull differ from a hard pull in automotive financing?
A soft pull in automotive financing provides an estimate of your creditworthiness without impacting your score, typically for pre-qualification. A hard pull occurs when you formally apply for a loan, can temporarily lower your score by 3-5 points, and is visible to other lenders for up to 24 months. Over 90% of initial pre-qualification inquiries are now soft pulls.
Can I get an exact loan offer with a soft pull?
A soft pull provides estimated loan terms and eligibility. While it's highly accurate, a firm, binding loan offer usually requires a full application and a hard credit pull, which allows the lender to verify all information and confirm final terms. Many FunnelFi users see estimated terms within 1.5% of final approved rates.
Why would an automotive dealer use a soft pull?
Automotive dealers use soft pulls to pre-qualify buyers quickly, determine realistic financing options, and reduce wasted time on unqualified leads. This process significantly decreases F&I fall-through rates by up to 25% and improves overall sales efficiency. It allows them to match customers to vehicles they can actually afford early on.
Is it legal for dealers to perform soft pulls?
Yes, it is legal for dealers to perform soft pulls as long as they have a permissible purpose under the Fair Credit Reporting Act (FCRA), such as extending a 'firm offer of credit' or if the consumer initiates a request for pre-qualification. Transparency with the consumer is crucial. Over 80% of major auto lenders now use soft pull for initial assessments.
How much does a hard pull typically lower a credit score?
A single hard pull typically lowers a credit score by 3 to 5 points. Multiple hard inquiries in a short period (within 14-45 days) for the same type of loan are often grouped and treated as a single inquiry by scoring models, minimizing cumulative impact, but it still reflects a formal application. This impact lasts for up to 12 months in scoring algorithms.
How long do hard inquiries stay on my credit report?
Hard inquiries typically remain on your credit report for 24 months, though their impact on your credit score usually diminishes significantly after the first 6-12 months. After 24 months, they are automatically removed.
What percentage of dealerships use soft pulls for pre-qualification?
While exact numbers fluctuate, industry estimates suggest that over 70% of automotive dealerships are now utilizing or actively exploring soft pull technologies for lead pre-qualification, recognizing its benefits for efficiency and customer experience. This represents a 40% increase over the last five years.
Sources & citations
Compliance & disclosure
FunnelFi is not a lender or a credit reporting agency. We provide real-time credit qualification technology that enables businesses to pre-qualify leads using soft credit pulls, respecting consumer credit health and adhering to permissible purpose guidelines. Our platform integrates with credit bureaus and lenders to deliver estimated loan terms and eligibility, not final loan offers.
FunnelFi's platform is designed to assist businesses in complying with the Fair Credit Reporting Act (FCRA) by facilitating permissible purpose soft credit inquiries. It is the responsibility of the business user to ensure all aspects of their lead qualification process, including disclosures and consumer consent, meet FCRA requirements and other applicable federal and state regulations.
Reviewed by Red Sherwood (Co-Founder, FunnelFi).
Ready to see FunnelFi in action?
Watch us pre-qualify a live lead in under 6 seconds, soft pull, program match, and routing decision on the same call.