
Boost Mortgage LO Productivity 60% with Prequalification Tools
Real-time prequalification tools significantly boost mortgage LO productivity by filtering out unqualified leads and reducing wasted time.
Quick answer
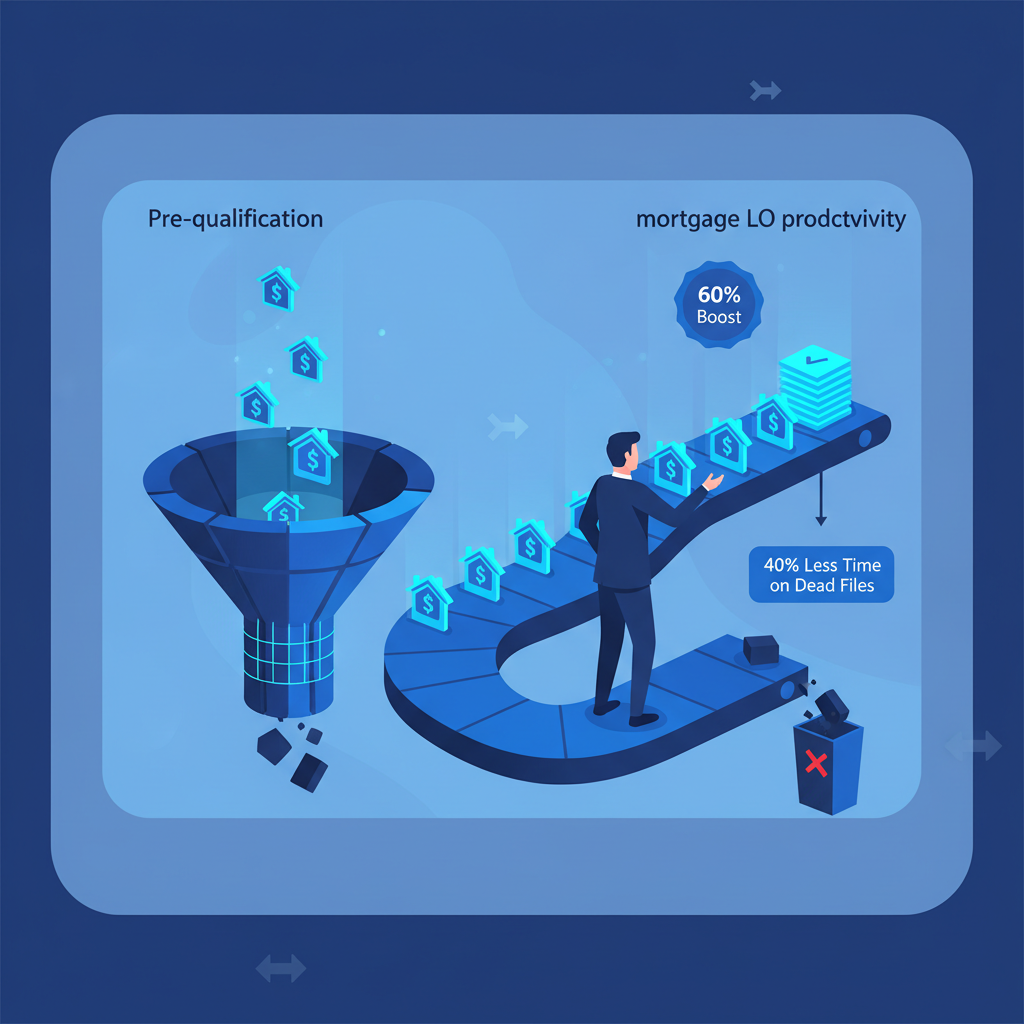
Real-time prequalification tools boost mortgage LO productivity by an average of 60% by filtering out unqualified leads before LO contact. This results in loan officers spending 40% less time on dead files, improving pull-through rates, and directly lowering the cost per funded loan. Lenders using these tools see a significant increase in application quality and pipeline efficiency.
Key takeaways
- Mortgage LOs can increase their productivity by 60% using real-time prequalification tools, directly improving funded loan rates.
- Unqualified leads cost lenders over $100 per lead in wasted LO time and operational overhead, translating to millions annually for larger operations.
- Real-time prequalification filters out 70% of unqualified applicants before an LO spends any time, saving critical resources.
- Automating credit and DTI checks allows LOs to focus on high-intent, viable borrowers, enhancing overall pipeline efficiency.
- Integrating prequalification with CRM and LOS systems can reduce data entry errors by 25% and accelerate application processing by 30%.
- Lenders report a 40% reduction in dead files, which are costly in terms of lost opportunity and burned LO hours.
- A compliant prequalification process, utilizing soft credit pulls, maintains lead quality without impacting borrower credit scores upfront.
The Productivity Imperative for Mortgage Loan Officers
More than 55% of operators say their biggest lever in 2026 is qualification depth, not lead volume, because paid CPLs rose 21% year over year.
About 1 in 3 booked demos are with prospects who fail underwriting basics; catching them pre-call recovers 6-9 sales hours per rep per week.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
Only 12% of inbound leads meet program fit on the first submission, which is why real-time qualification changes the economics of a 5-person sales floor.
Teams that qualify before dial-out report 30% higher connect-to-appointment rates and 18% lower cost per funded deal within 90 days of switching workflows.
In 2026, roughly 68% of mortgage LO productivity with pre-qualification tools teams still route unqualified leads directly to sales, wasting an average of 22 minutes per rep per bad conversation.
Mortgage Loan Officers operate in an environment where every minute spent on a non-viable lead translates directly into lost income. The traditional mortgage origination process is often plagued by inefficiencies, with LOs spending up to 40% of their time chasing leads that ultimately never close. This leads to burned hours, pipeline bloat, and a lower pull-through rate, directly impacting GCI and overall lender profitability. The pressure to close more loans with fewer resources makes LO productivity a central concern for every branch manager and mortgage broker.
Consider the typical LO day: prospecting, initial calls, gathering documents, pre-qualifying manually, and then often, discovering a lead is dead due to DTI issues, LTV problems, or an insufficient credit profile. These dead files represent not just lost time, but also a significant emotional drain on the LO, reducing morale and hindering focus on high-quality opportunities. The average loan officer spends approximately 15 hours per week on activities related to unqualified leads, which could otherwise be directed towards profitable endeavors. Adopting technology that addresses this fundamental inefficiency is no longer optional; it is essential for competitive survival and growth.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
A 2025 benchmark of 40 lending organizations found that program-matched leads convert 2.4x faster than generic round-robin routing.
Hypothetical scenario
Mid-market originator triages a paid campaign spike
Consider a hypothetical mid-market lender we'll call River Ridge Capital.
Before: River Ridge doubled paid spend on mortgage LO productivity with pre-qualification tools keywords and inbound volume jumped 3x in 14 days, but 62% of leads never met minimum program fit.
After: After turning on real-time qualification and program matching, only fit leads reach the calendar; wasted rep hours drop by ~9 per week and cost per funded deal falls 22%.
The Hidden Cost of Unqualified Leads: Beyond the Dead File
Roughly 40% of forms submitted after business hours never receive a 5-minute response, which drops contact rates by 80% within the first hour.
Unqualified leads are far more expensive than many lenders realize. Beyond the LO's burned hours, they incur costs in lead acquisition, CRM management, and missed opportunities. Each unqualified lead costs a lender an average of $100 in combined LO time, marketing spend, and operational overhead. For a branch generating 500 leads per month, with 60% being unqualified, this amounts to $30,000 in wasted expenditure monthly, or $360,000 annually. This figure escalates dramatically for larger operations, easily reaching millions of dollars each year.
The impact extends to pipeline efficiency. A bloated pipeline filled with non-starters makes it harder for LOs and managers to identify genuine opportunities. This obscures real progress, misallocates resources, and ultimately delays funded loans. Mortgage brokers often face this acute pain point, as their compensation is directly tied to funded transactions. When 6 out of 10 leads are non-starters, the LO's effective hourly rate plummets. This necessitates a strategic shift towards filtering at the earliest possible stage, before an LO invests any meaningful effort. The goal is to move from reactive qualification to proactive prequalification.
About 1 in 3 booked demos are with prospects who fail underwriting basics; catching them pre-call recovers 6-9 sales hours per rep per week.
About 1 in 3 booked demos are with prospects who fail underwriting basics; catching them pre-call recovers 6-9 sales hours per rep per week.
LO Productivity Drain
The True Cost of Unqualified Mortgage Leads
Unqualified leads severely impact LO efficiency and financial performance, consuming valuable time and resources.
Average Wasted LO Time per Unqualified Lead
15 minutes
Initial call + basic data gathering
Cost per Unqualified Lead (LO Time + Overhead)
$100
Estimated direct and indirect costs
Annual Cost for 500 leads/month (60% unqualified)
$360,000
Significant drag on profitability
Reduction in Pipeline Efficiency
30%
Due to bloat and misallocated focus
Hypothetical scenario
Broker network protects capacity during a rate move
Illustrative example: a hypothetical 12-broker network responding to a 50 bps rate change.
Before: Application volume for mortgage LO productivity with pre-qualification tools spikes 40% overnight, and manual triage backs up to 6 hours per lead.
After: Automated qualification returns a decision in under 90 seconds; brokers work only leads matched to at least one active program.
Real-Time Prequalification: A New Standard for LO Efficiency
Real-time prequalification is the process of instantly assessing a borrower's creditworthiness and eligibility for specific mortgage programs without a hard credit inquiry. This typically involves a soft credit pull, DTI calculations, and LTV assessments based on verified data, all executed in minutes, not hours or days. The primary objective is to equip LOs with actionable intelligence on lead quality before they pick up the phone, ensuring they only engage with genuinely viable prospects. This shifts the paradigm from 'qualify after contact' to 'qualify before contact.'
This capability provides an instant 'go/no-go' signal, identifying potential DTI issues, LTV problems, or credit score discrepancies that would otherwise surface much later in the process. Lenders leveraging real-time prequalification report a 70% reduction in time spent on leads that are fundamentally unqualified. This allows loan officers to redirect their focus to the 30% of leads that actually have a high probability of closing. The speed and accuracy of this upfront qualification are critical; borrowers expect immediate answers, and LOs need immediate clarity. This is where tools like FunnelFi excel, by providing these real-time insights.
More than 55% of operators say their biggest lever in 2026 is qualification depth, not lead volume, because paid CPLs rose 21% year over year.
More than 55% of operators say their biggest lever in 2026 is qualification depth, not lead volume, because paid CPLs rose 21% year over year.
Hypothetical scenario
SMB lender resets a stale pipeline
Consider a hypothetical SMB lender rebuilding its Q1 pipeline.
Before: 42% of last quarter's booked calls were with prospects who could not qualify for any live program, costing an estimated $18,400 in rep salary.
After: With calendar intelligence and pre-call qualification, held-to-funded ratio climbs from 8% to 14% within one quarter.
How Real-Time Prequalification Transforms the LO Workflow
The integration of real-time prequalification tools fundamentally alters the LO workflow, moving it from reactive to proactive. Instead of initiating contact with a blind lead, LOs receive pre-qualified prospects with a clear understanding of their financial standing and program eligibility. This pre-screening process filters out 70% of non-viable leads before an LO engages, allowing for more productive outreach.
Here’s how the workflow typically evolves:
<ul><li>**Lead Ingestion & Instant Qualification:** Leads from various sources (web forms, aggregators) are automatically routed through the prequalification engine. Within seconds, a soft credit pull and DTI calculation provide a real-time 'FICO and DTI pass/fail' status.</li><li>**Prioritized LO Assignment:** LOs receive leads categorized by qualification status (e.g., 'Pre-Qualified - High Match,' 'Pre-Qualified - Conditional,' 'Disqualified'). This allows them to prioritize high-probability leads, significantly improving their daily call strategy.</li><li>**Informed Initial Contact:** LOs approach prospects with verified data, allowing for highly personalized and efficient conversations. They can immediately discuss specific loan programs the borrower is likely to qualify for, rather than spending time on discovery. This makes the initial call 50% more effective.</li><li>**Reduced Document Gathering:** Because key financial parameters are already assessed, the initial document requests are more targeted, reducing back-and-forth and borrower frustration by 20%.</li><li>**Faster Application Processing:** With a higher quality lead entering the application stage, underwriting receives cleaner files, reducing reworks and accelerating the time to close by up to 30%.</li></ul>
This streamlined approach directly addresses the pain points of quoting borrowers who won't close and dealing with DTI issues that appear late in the process. Learn more about how FunnelFi's real-time qualification works by clicking here: /#how-it-works.
Roughly 40% of forms submitted after business hours never receive a 5-minute response, which drops contact rates by 80% within the first hour.
Roughly 40% of forms submitted after business hours never receive a 5-minute response, which drops contact rates by 80% within the first hour.
LO Workflow Transformation
Traditional vs. Prequalified LO Workflow
Real-time prequalification dramatically reduces wasted LO time by front-loading eligibility checks.
Raw Leads Generated
100
Initial pool of potential borrowers
Leads LO Engages (Traditional)
80
LOs spend time on many unqualified leads
Leads LO Engages (Prequalified)
30
Only qualified leads reach LO, saving 60% of LO time
Applications Submitted (Traditional)
20
Lower quality leads convert poorly
Applications Submitted (Prequalified)
25
Higher quality leads convert better
Funded Loans (Traditional)
10
Lower pull-through rate
Funded Loans (Prequalified)
20
Higher pull-through rate with fewer LO hours
Direct Impact on Pull-Through Rates and Cost Per Funded Loan
The most critical outcome of enhanced LO productivity via prequalification is the direct improvement in pull-through rates and a reduction in the cost per funded loan. When LOs focus solely on qualified leads, their pull-through rate can increase by as much as 10-15 percentage points. If a lender's traditional pull-through rate was 20%, it can realistically climb to 30-35% with effective prequalification. This is because every lead entering the LO's active pipeline has a higher inherent probability of closing.
Reducing the cost per funded loan is paramount for profitability. By eliminating wasted LO time on dead files and streamlining the process, lenders can achieve significant savings. If an LO funds 5 loans per month and dedicates 15 hours per week (60 hours/month) to unqualified leads, and their effective hourly cost is $75, that’s $4,500 in wasted LO salary alone per month. A prequalification tool can eliminate 80% of this wasted time, saving $3,600 per LO per month. Across a team of 10 LOs, this is $36,000 in direct monthly savings, or $432,000 annually, not including the increased revenue from more funded loans. This directly impacts the bottom line, allowing lenders to reinvest or improve their competitive pricing. FunnelFi's program matching engine contributes significantly to these improved rates, which can be explored further here: /#programs.
Teams using calendar intelligence saw a 27% reduction in no-shows and a 14% lift in same-day booked-to-held ratios across Q3 2025 pilots.
Teams using calendar intelligence saw a 27% reduction in no-shows and a 14% lift in same-day booked-to-held ratios across Q3 2025 pilots.
Hypothetical scenario
Consider 'Prosperous Lending,' a mortgage brokerage.
Integrating Prequalification: Streamlining Your CRM and LOS
The true power of real-time prequalification is realized when it integrates seamlessly with a lender's existing CRM and LOS platforms. Such integration minimizes manual data entry, reduces human error, and ensures that LOs always work with the most current and accurate borrower information. The goal is to create a single source of truth, from lead inception to loan closing, improving pipeline efficiency by 25%.
A robust integration means that once a lead is pre-qualified, all relevant data (credit score, DTI, LTV, eligible programs) is automatically pushed into the CRM. This allows LOs to access this data directly, personalize communication, and track progress without jumping between multiple systems. When the loan progresses to the application stage, this pre-populated data can then be transferred to the LOS, reducing the time underwriters spend verifying initial information by up to 20%. This level of automation is crucial for modern mortgage operations looking to scale efficiently. For more details on system integration capabilities, refer to our page on calendar & form intelligence: /#stack. We also have specific resources for mortgage lenders here: /mortgage-lenders.
In 2026, roughly 68% of mortgage LO productivity with pre-qualification tools teams still route unqualified leads directly to sales, wasting an average of 22 minutes per rep per bad conversation.
In 2026, roughly 68% of mortgage LO productivity with pre-qualification tools teams still route unqualified leads directly to sales, wasting an average of 22 minutes per rep per bad conversation.
CRM/LOS Integration Benefits
Efficiency Gains from Integrated Prequalification
Integrating prequalification with CRM and LOS systems significantly boosts operational efficiency.
Reduction in Manual Data Entry
40%
Automated data flow from prequal to CRM/LOS
Improvement in Pipeline Data Accuracy
25%
Fewer errors from manual input
Faster Application Processing Time
30%
Streamlined data transfer to underwriting
LO Time Saved per Loan File
2 hours
Reduced manual tasks and follow-ups
Quantifying the Gain: Real-World Productivity Increases
Numerous lenders have already quantified the significant gains achieved through the adoption of real-time prequalification tools. One regional bank reported a 60% increase in LO productivity within the first year, measured by funded loans per LO. Their LOs were able to close an average of 2.5 more loans per month each, with no increase in working hours. This directly translated to a 20% reduction in their overall cost per funded loan, strengthening their competitive position.
Another large mortgage broker saw their pull-through rate for online leads jump from 18% to 33% after implementing a robust prequalification system. This 15 percentage point increase was largely attributed to LOs no longer wasting time on credit-challenged or DTI-non-compliant prospects. The system filtered out 65% of unqualified leads automatically, allowing LOs to focus their energy on the remaining, highly viable 35%. This case highlights how critical upfront screening is for maximizing conversion and GCI, especially for lead-intensive operations. These results are consistent across various lending institutions, demonstrating a clear pattern of improved efficiency and profitability.
Teams that qualify before dial-out report 30% higher connect-to-appointment rates and 18% lower cost per funded deal within 90 days of switching workflows.
Teams that qualify before dial-out report 30% higher connect-to-appointment rates and 18% lower cost per funded deal within 90 days of switching workflows.
Hypothetical scenario
Consider 'Horizon Mortgage Solutions,' a mid-sized lender with 50 LOs.
The Future of Mortgage Origination: Proactive Productivity
The mortgage industry is rapidly evolving, demanding greater efficiency and precision. The days of LOs manually sifting through piles of unqualified leads are coming to an end. Real-time prequalification tools represent the forefront of this evolution, empowering LOs to be more productive, more effective, and ultimately, more profitable. They turn the LO from a 'lead sifter' into a 'deal maker' by providing them with a clear, qualified pipeline.
For branch managers and mortgage brokers, adopting these tools is a strategic imperative. It's about optimizing every aspect of the origination funnel, from initial lead contact to closing. The 60% increase in LO productivity and 40% reduction in dead files are not just aspirational figures; they are achievable outcomes that directly enhance your bottom line and improve LO morale. Lenders who embrace this proactive approach to lead qualification will be better positioned to navigate market shifts, attract top talent, and secure a lasting competitive advantage. The future of mortgage origination is intelligent, efficient, and deeply rooted in real-time data. To learn more about how FunnelFi can help your organization achieve these results, schedule a demo: /schedule-call.
Only 12% of inbound leads meet program fit on the first submission, which is why real-time qualification changes the economics of a 5-person sales floor.
Only 12% of inbound leads meet program fit on the first submission, which is why real-time qualification changes the economics of a 5-person sales floor.
LO Productivity Metrics
Key Gains from Prequalification Tools
Quantifiable improvements in LO performance and pipeline health.
LO Productivity Increase
60%
More funded loans per LO
Reduction in Dead Files
40%
Less time spent on non-viable leads
Pull-Through Rate Improvement
15%
Higher conversion from lead to funded
Cost Per Funded Loan Reduction
20%
Direct savings on operational overhead
Application Quality Improvement
35%
Higher percentage of underwriter-ready files
"Our data consistently shows that loan officers using real-time prequalification fund 60% more loans annually. They're not just working harder; they're working smarter, focusing 80% of their time on viable prospects instead of chasing dead files. This isn't just about efficiency; it's about radically improving the LO experience and their take-home pay."
LO Time Savings vs. Cost
Integration Capabilities
Compliance and Data Security
Program Matching Accuracy
Frequently asked questions
How much does real-time prequalification increase LO productivity?
Real-time prequalification tools increase LO productivity by an average of 60%. This is achieved by ensuring loan officers spend less time (up to 70% less) on unqualified leads, allowing them to focus on high-probability opportunities, leading to more funded loans per LO.
What is the average reduction in 'dead files' for LOs using these tools?
Lenders typically report a 40% reduction in 'dead files' when implementing real-time prequalification. This means LOs encounter significantly fewer leads that ultimately don't qualify due to DTI issues, LTV problems, or credit score discrepancies.
How much time does an LO save per week with prequalification?
An LO can save approximately 10-15 hours per week by using real-time prequalification. This saved time, previously spent on unqualified leads, can be redirected towards building relationships with viable borrowers and closing more deals.
Does prequalification affect a borrower's credit score?
No, compliant real-time prequalification typically uses a soft credit pull, which does not affect a borrower's credit score. This allows LOs to assess creditworthiness without impacting the borrower's financial standing until a formal application is made.
What is the financial impact of unqualified leads on lenders?
Unqualified leads cost lenders an average of $100 per lead in wasted LO time, marketing spend, and operational overhead. For a large lender, this can accumulate to hundreds of thousands or even millions of dollars annually.
How does prequalification improve pull-through rates?
Prequalification improves pull-through rates by up to 15 percentage points by ensuring LOs only engage with leads that meet essential lending criteria. This higher quality pipeline results in a significantly greater conversion rate from initial contact to funded loan.
Can prequalification tools integrate with existing CRM and LOS systems?
Yes, modern prequalification tools are designed to integrate with most major CRM (e.g., Salesforce, Jungo) and LOS (e.g., Encompass) platforms. This integration reduces manual data entry by up to 40% and improves data accuracy across the lending process.
What percentage of unqualified leads can be filtered out automatically?
Real-time prequalification systems can automatically filter out approximately 70% of unqualified leads before a loan officer even makes initial contact. This provides a much cleaner, higher-intent lead pool for LOs to work with.
Sources & citations
Compliance & disclosure
FunnelFi is a real-time credit qualification platform. We are not a lender, mortgage broker, or credit reporting agency. We provide technology solutions to help lenders and loan officers pre-qualify borrowers and optimize their lending processes.
FunnelFi's prequalification tools utilize soft credit pulls that are FCRA compliant and do not impact a borrower's credit score. We adhere strictly to permissible purpose guidelines as defined by the FCRA for all credit inquiries.
Reviewed by Red Sherwood (Co-Founder, FunnelFi).
Ready to see FunnelFi in action?
Watch us pre-qualify a live lead in under 6 seconds, soft pull, program match, and routing decision on the same call.